featured article — Barrons Top 150 Financial Advisers 2025
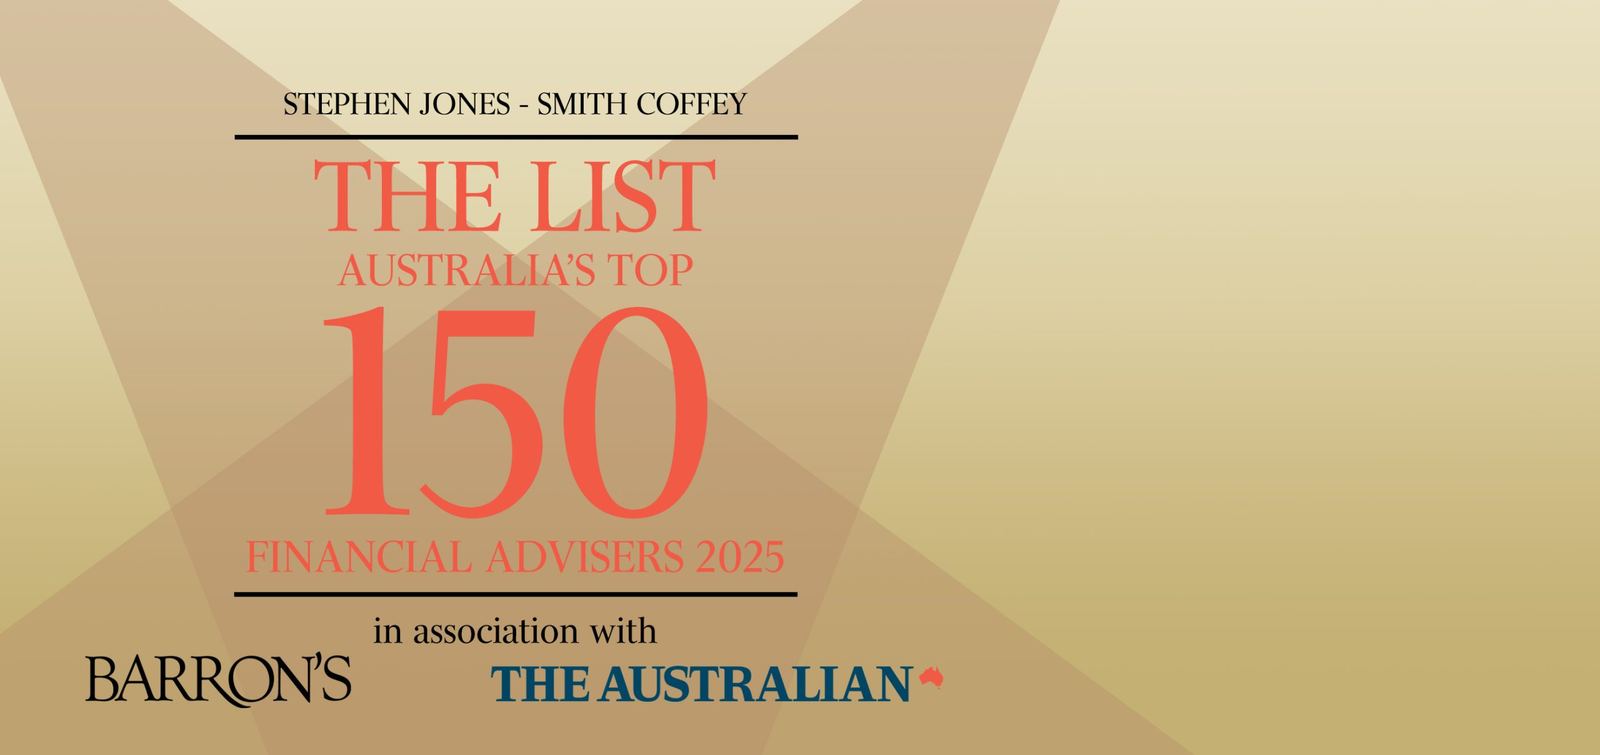
Smith Coffey is delighted to congratulate Stephen Jones on being recognised in Barron's Top 150 Financial Advisers 2025, ranking#59 in Australia. This recognition highlights Stephen's longstanding commitment to delivering exceptional financial advice and trusted client relationships over the past 30 years. Read the Full Article
by the adminread now
featured article — ATO Crackdown on Holiday Homes: What Property Owners Need to Know
The Australian Taxation Office (ATO) has introduced a significant shift in how tax deductions apply to holiday homes. These changes, outlined in TR 2026/1, are designed to address widespread errors in claiming deductions and represent a much stricter approach than in the past. If you own a holiday rental property, it’s critical to understand how these changes may affect your tax position.
A Fundamental Change in Approach
Historically, the ATO allowed owners to apportion expenses based on rental versus private use. Under the new approach, the ATO may instead apply Section 26-50, which treats holiday homes as a “leisure facility”. This means that most property-related deductions can be denied entirely, even if the property generates some rental income.What Is Considered a Holiday Home?
A property is likely to be classified as a holiday home (leisure facility) if it is used for private purposes at any time, including:- Use by the owner or family
- Use by friends or relatives (free or discounted)
- Even minimal private use (e.g. a few nights per year)
When Are Deductions Denied?
If a property is classified as a holiday home and is not mainly used to derive rental income, Section 26-50 can apply.Deductions that may be denied:
- Interest on loans
- Council rates
- Land tax
- Insurance
- Repairs and maintenance
Deductions that may still be claimed:
- Platform fees (Airbnb, Stayz)
- Property management fees
- Advertising costs
- Cleaning between tenants
The Key Test: “Mainly Used to Derive Rental Income”
The critical factor is whether the property is mainly used to earn rental income. If the answer is yes:- Normal deduction rules apply (with apportionment where relevant)
- Most deductions are denied under Section 26-50
How the ATO Determines “Mainly Used”
The ATO applies a holistic assessment, not just a simple time-based calculation. Key factors include:- Actual pattern of use throughout the year
- Whether the property is available during peak rental periods (e.g. Christmas, school holidays)
- Level of private use or availability for private use
- Efforts to maximise rental income (pricing, responsiveness, marketing)
ATO Compliance Focus: High-Risk Behaviours
The ATO is specifically targeting arrangements where:- Peak periods (e.g. Christmas, Easter, school holidays) are blocked out for private use
- The property is not genuinely available for rent
- Owners impose unreasonable restrictions (e.g. excessive pricing or conditions)
- Rental activity is passive or limited
- Private use is prioritised over commercial returns
Risk Rating: Green, Amber, Red
The ATO has introduced a practical compliance framework to assess risk:Low Risk (Green Zone)
- High occupancy, especially during peak periods
- Minimal private use
- Clear focus on maximising rental income
Medium Risk (Amber Zone)
- Increased private use by owners, family or friends
- Some missed rental opportunities
- Property is used during peak income-producing periods
- Less active management
High Risk (Red Zone)
- Property primarily used for personal holidays
- Peak periods blocked out
- Limited effort to rent commercially
- Unreasonable restrictions are placed on potential renters
- Limited or no attempt to increase the occupancy of the property
When Do These Changes Apply?
The ATO confirms they will not devote compliance resources for expenses incurred in relation to holiday homes before 1 July 2026, unless there is evidence of avoidance, fraud or inappropriate advantages gained from this transitional compliance approach.What You Should Do Now
If you own a holiday rental property, consider:- Reviewing how often the property is used privately
- Ensuring it is available for rent during peak demand periods
- Minimising non-commercial use
- Actively managing listings to maximise occupancy
- Keeping detailed records of availability and bookings
read now
featured article — Personal Services Income for Doctors & Dentists: Your Questions Answered
If you work as a doctor, dentist, locum, or contractor, particularly through a company or trust, you have certainly come across the term Personal Services Income (PSI), one of the most important tax concepts affecting healthcare professionals in Australia. For many healthcare professionals, it is one of the most misunderstood areas of Australian tax law, and getting it wrong can be costly. This guide answers the most common questions we hear from doctors and dentists about PSI rules in Australia, including what is personal services income, how the Personal Services Business (PSB) tests work, what happens if the rules apply to your income, when to seek professional advice, and more. Let’s explore answers for them here.
What is Personal Services Income (PSI)?
Personal services income is an income you earn mainly through your individual skills, knowledge, or efforts, rather than through the sale of goods or assets. Personal services income for dentists and doctors commonly includes:- Medical consulting
- Dental services
- Locum work
- Contracting arrangements
- Specialist services
- Sole practitioner work
Does PSI Apply to Doctors and Dentists in Australia?
Yes, PSI rules in Australia apply to the majority of doctors and dentists, particularly if you work as a locum, contractor, or through a private practice structure. Here are some common examples where PSI is likely to apply:| Scenario | PSI Applicability |
|---|---|
| Locum doctor working short-term contracts | Yes |
| A dentist contracted to one clinic | Yes |
| Specialist billing through own company | Often yes |
| Medical practice employing multiple practitioners and staff | Possibly not |
What is the Difference Between PSI and a Personal Services Business (PSB)?
PSI (Personal Services Income) is a classification of income, specifically, the income derived from your personal skills or efforts. And PSB (Personal Services Business) is a tax status that can exempt you from the PSI rules for a given income year. Think of it this way: PSI describes what your income is; PSB status determines whether the restrictions that normally come with that income apply to you.| Scenario | PSI Applicability |
|---|---|
| Locum doctor working short-term contracts | Yes |
| A dentist contracted to one clinic | Yes |
| Specialist billing through own company | Often yes |
| Medical practice employing multiple practitioners and staff | Possibly not |
What Are the PSB Tests and How Do I Know If I Pass?
There are four Personal Services Business tests set out by the ATO. Passing one (plus satisfying the 80% rule where required) allows you to self-assess as a PSB for that income year.The 80% Rule
Before looking at each test, it is important to understand the 80% rule. This rule states that no more than 80% of your PSI in an income year can come from a single client (and their associates). If more than 80% comes from one source, you cannot use most of the PSB tests unless you also apply for a PSB Determination from the ATO This is particularly important for healthcare professionals who work predominantly at one hospital, clinic, or dental practice. Now, let’s understand all four PSB tests.| Personal Services Business tests | Key Requirements | 80% Rule Needed? |
|---|---|---|
| Results Test | 75%+ of PSI paid for specific results, with own tools, rectifying errors at own cost | No. Pass this, and you can self-assess as a PSB |
| Unrelated Clients Test | PSI received from 2+ unrelated clients via genuine offers to the public | Yes. Must also pass the 80% rule |
| Employment Test | 20%+ of principal work done by others, or at least one apprentice for 6+ months | Yes. Must also pass the 80% rule |
| Business Premises Test | Dedicated business premises used solely to earn PSI, separate from home and clients | Yes. Must also pass the 80% rule |
What Happens if the PSI Rules Apply to My Income?
If the PSI rules apply and you do not qualify as a PSB, there are important tax consequences:- Income attribution: Your income is attributed back to you as an individual, even if it has been paid to a company or trust.
- Restricted deductions: You cannot claim many deductions you might otherwise claim through a business entity. Expenses such as rent, mortgage interest, and some home office costs are typically off the table.
- No income splitting: You cannot distribute income to a spouse, family member, or beneficiary at a lower tax rate via a trust or company.
- Personal tax rates apply: The full income is taxed at your marginal rate as an individual.
Can I Still Use a Company or Trust if I Earn PSI?
Yes. A company or trust can still be used for operational, legal, or administrative reasons. But it is important to understand what having a structure does and does not do for you. If the PSI rules do apply:- The income is attributed back to you personally, regardless of the entity
- You cannot use the structure to split income with associates or beneficiaries
- Certain deductions available to the entity are disallowed
- The PSI restrictions do not apply for that income year
- You can legitimately retain income in the structure
- You have more flexibility around distributions and deductions
How Do I Apply for a Personal Services Business Determination (PSBD)?
A Personal Services Business Determination (PSBD) is a formal decision made by the Commissioner of Taxation that grants you PSB status for a specific income year, even if you cannot self-assess as a PSB using the standard tests. You may want to apply for a PSBD if:- You are uncertain whether you will pass any of the four PSB tests
- Unusual circumstances (such as a pandemic, illness, or industry disruption) prevented you from passing a test you would otherwise meet
- You passed the Unrelated Clients Test but failed the 80% rule due to circumstances beyond your control
read now
Videos
featured video — Our Engagement Process
We’re here to make managing your finances easier
by the FSD Team March 3 2021
Financial Advice vs Other Advice
It’s important to get the right financial advice
by the FSD Team March 3 2021
Jeff Chin Investment Performance & Positioning
We often prepare market updates which are exclusively sent to Smith Coffey clients. Click below to see a short excerpt from our latest video on investment performance and positioning.
by the FSD Team March 3 2021
Introduction to Stephen Jones
Save valuable time by letting me handle all aspects of your finance in one place.
by the FSD TeamArticles of Interest
March 3 2021
Barrons Top 150 Financial Advisers 2025
Smith Coffey is delighted to congratulate Stephen Jones on being recognised in Barron’s Top 150 Financial Advisers 2025, ranking#59 in Australia. This recognition highlights Stephen’s longstanding commitment to delivering exceptional financial advice and trusted client relationships over the past 30 years. Read the Full Article
by the admin
March 3 2021
ATO Crackdown on Holiday Homes: What Property Owners Need to Know
The Australian Taxation Office (ATO) has introduced a significant shift in how tax deductions apply to holiday homes. These changes, outlined in TR 2026/1, are designed to address widespread errors in claiming deductions and represent a much stricter approach than in the past. If you own a holiday rental property, it’s critical to understand how […]
by the admin
March 3 2021
Personal Services Income for Doctors & Dentists: Your Questions Answered
If you work as a doctor, dentist, locum, or contractor, particularly through a company or trust, you have certainly come across the term Personal Services Income (PSI), one of the most important tax concepts affecting healthcare professionals in Australia. For many healthcare professionals, it is one of the most misunderstood areas of Australian tax law, […]
by the FSD TeamFact Sheets
The Changing World Of Financial Services Can Be Overwhelming...
We will provide a bespoke financial plan to help you achieve your goals.
Smith Coffey specialise in the needs of medical and dental professionals. We provide a 360-degree financial service.